
Emerald Pages
◆
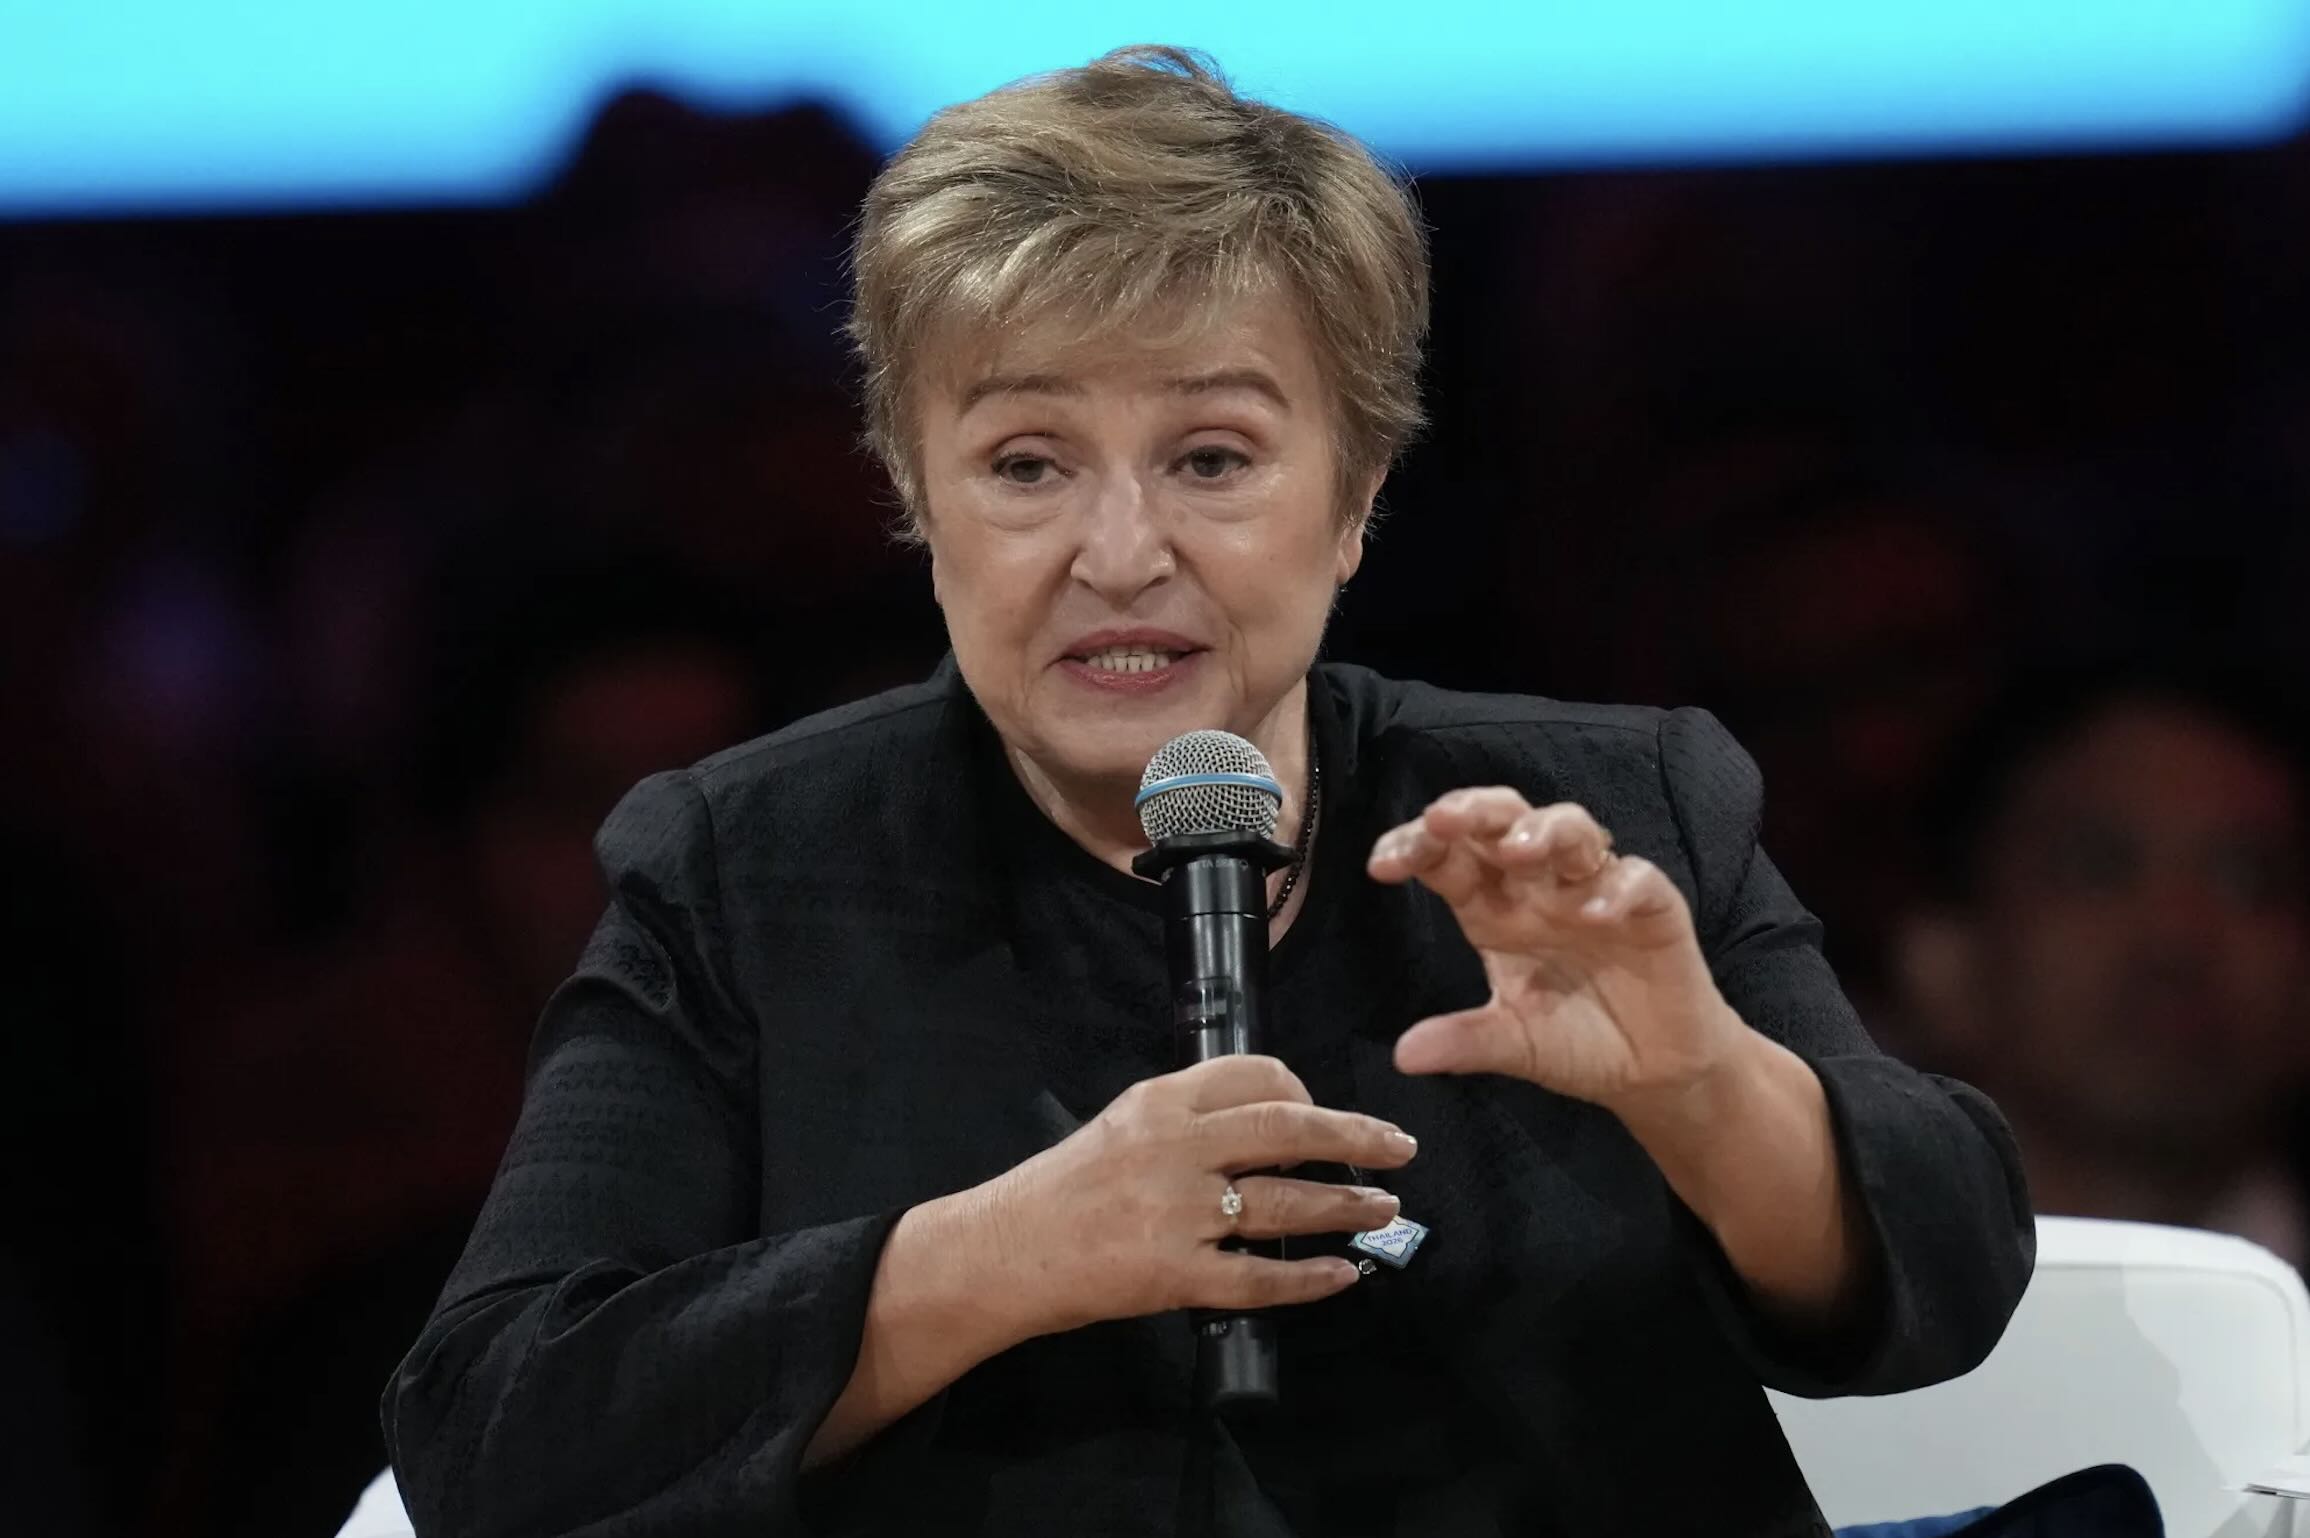
The chief of the International Monetary Fund (IMF), Kristalina Georgieva | Photo: AP Photo
The global economy is walking a tightrope. Central banks around the world are raising interest rates in unison, the International Monetary Fund is warning of a potential AI-driven market correction, and a single initial public offering scheduled for November could be the catalyst that tips it all over.
The pieces are in place for a recession by next year. The question is no longer whether the risk exists—it's whether anything can stop it.
Central banks have shifted back into a hawkish stance, creating a high-risk environment where aggressive monetary policy meets a highly leveraged tech bubble. The U.S. Federal Reserve, under Chair Kevin Warsh, pushed through a quarter-point hike in September—the first since 2023—and signaled more are coming. The European Central Bank raised rates as Eurozone inflation ticked up to 3.8%. The Reserve Bank of Australia hiked after fuel spikes pushed domestic headline inflation to 4.6%.
As Warsh noted at the IMF meetings in Bangkok, this is a "synchronous tightening." When one country raises rates, it cools domestic demand. When everyone raises rates simultaneously, it restricts global credit flows, compounding the drag on international trade and global GDP.
The trigger for this coordinated tightening is a persistent inflation problem driven by energy shocks from the Middle East conflict—Brent crude recently hit $110 a barrel as the U.S.-Iran war restricts Strait of Hormuz shipments—and the massive near-term demand shock of the AI infrastructure boom itself.
The IMF's Warning
In its Global Financial Stability Report released this month, the IMF explicitly warned that the massive surge in artificial intelligence spending has created a potential bubble risk that could trigger a global financial correction. The Fund named a potential AI market correction as one of the three primary near-term catalysts for market turmoil.
The IMF's core concerns are stark:
- The $1.4 Trillion Financing Loop: Major cloud service providers are heavily financing smaller AI firms, who in turn use those funds to buy products back from those same hyperscalers.
- Skyrocketing Tech Debt: Tech firms' share of investment-grade bond issuance skyrocketed from less than 1% to 10% in just a two-year span.
- Global Macro Spillover: A severe AI unwind could erase enough investor wealth to reduce global GDP by up to 1.1% and trigger a 20% drop in U.S. equities by 2028.
Wall Street disagrees. Analysts from Goldman Sachs, Morgan Stanley, and JPMorgan have countered that big tech companies remain deeply profitable in their core businesses, generate massive cash flows, and hold strong credit ratings that differentiate today's tech boom from the late-1990s dot-com crash.
But the IMF is providing the unvarnished mathematical reality. The U.S. government cannot publicly attack the very sector that is mathematically keeping its headline economic numbers positive—so Washington is quietly drafting contingency plans behind closed doors, hoping the sector can pivot to profitability before the clock runs out.
The Paper Growth Illusion
AI is effectively responsible for masking a broader economic slowdown. According to macroeconomic assessments by institutions like Deutsche Bank and BNP Paribas, without the massive surge in AI infrastructure spending, the United States economy would likely already be in a technical recession.
When a tech giant spends $5 billion building a data center in Ohio or Virginia, that entire amount is immediately factored into GDP as private business investment. GDP metrics don't care if that data center ever turns a profit—they only record that the money was spent.
This creates a stark division. On one side, AI capital expenditures and high-end stock market wealth effects keep aggregate GDP numbers positive. On the other side, small-to-medium businesses and the "mom-and-pop" retail economy are experiencing severe deterioration.
The Anthropic Catalyst
Anthropic's blockbuster IPO—reportedly scheduled for mid-to-late November—is shaped up to be the exact psychological catalyst that could puncture the AI bubble.
The warning signs are already flashing. Anthropic was aggressively aiming for a $2 trillion market cap. Following its latest financial disclosures, major prospective institutional investors are already pushing to slash that target by half a trillion dollars, down to $1.5 trillion. While Anthropic posted massive Q3 revenue of $16.8 billion, its sequential quarter-over-quarter growth slowed to 45%—compared to the staggering 140% growth it posted between Q1 and Q2. Wall Street is viewing this rapid deceleration as a major red flag.
Even more concerning: Anthropic is reportedly offering Blackstone a massive double-digit yield exceeding 10% to secure a $9 billion structured debt deal to lease hardware. Turning to high-interest, non-traditional junk-rate financing while preparing for an IPO signals immense underlying cash burn.
When an asset class is in a bubble, it can survive on abstract hype as long as companies remain private. A massive public listing forces the market to price the company based on actual, transparent cash-flow math.
If Anthropic prices severely below expectations or crashes immediately after hitting the Nasdaq, it will serve as concrete proof that the market has drastically overvalued AI capabilities. A broken Anthropic IPO would trigger an immediate re-evaluation of its major public backers, specifically Alphabet and Amazon, both of which hold massive paper gains on their balance sheets from early Anthropic investments. To protect their own stock prices, these hyperscalers would be forced to immediately curb their aggressive multi-billion-dollar infrastructure spending.
The Structural Fault Lines
The AI bubble provides the psychological trigger and the labor market shows the initial demographic fractures—Black unemployment jumped a full percentage point to 7.0% in September—but the corporate bond maturity wall, commercial real estate crisis, and private credit shadow market represent the massive structural fault lines.
For the last two years, corporate borrowers utilized a strategy called "extend and pretend"—using short-term loan modifications to push off defaults in the hope that central banks would cut interest rates back down. With the Federal Reserve instead raising rates and the 10-year Treasury yield scaling above 5%, that strategy has officially failed.
- The Commercial Real Estate Cliff: A staggering $1.26 trillion of U.S. commercial real estate mortgages will mature and require refinancing in 2027 alone. These properties secured their loans at average interest rates between 4.1% and 4.7%. Today, refinancing a commercial asset hovers around 6.5% to 7%+, meaning debt-servicing costs will instantly skyrocket by up to 50% for landlords already facing historically depressed office occupancy rates.
- The Corporate Bond Maturity Wall: Non-financial U.S. corporations are staring down a multi-year $4.3 trillion cliff of maturing corporate bonds between 2027 and 2031. High-yield (junk) bond maturities balloon from $68.5 billion in 2027 to $314.1 billion by 2029. For lower-rated borrowers, PIMCO reports that coupon interest payments will roughly double if refinanced at today's index yields.
- The Shadow Banking Risk: Private investment funds are heavily exposed to middle-market borrowers. Fitch Ratings explicitly noted that credit quality in Business Development Company loan portfolios is actively weakening, with non-accruals climbing and funds increasingly forced to accept Payment-in-Kind income—meaning instead of receiving actual cash interest from struggling borrowers, they are accepting more debt paper.
The 2027 Recession
If a pivotal event like a fractured Anthropic IPO triggers a broad-based tech contraction in November 2026, the traditional lag of monetary policy ensures the full economic impact would hammer the global and domestic economy next year.
- Q4 2026 (The Shock): A severe valuation markdown or postponement of the Anthropic listing breaks market psychology. Equity markets slide as tech giants systematically reassess their paper returns, forcing an immediate deceleration in their record-high infrastructure capital expenditures.
- Q1 2027 (The Debt Squeeze): Because tech companies heavily ramped up investment-grade bond issuance to pay for chips and data centers, a cooling sector triggers a wave of corporate credit downgrades. Banks, already facing elevated benchmark interest rates, sharply tighten credit standards.
- Q2 2027 (The Labor & Spending Drag): Deprived of easy capital, the tech sector and its immediate supply chains initiate severe hiring freezes and mass layoffs. Combined with a year-long "quiet recession" in non-AI sectors, consumer confidence—already hitting historic lows—completely flatlines.
- Q3–Q4 2027 (Formal Recession): As massive drops in consumer spending ripple across retail, services, and manufacturing, the aggregate U.S. GDP growth turns negative.
No Safety Net
The defining feature of this specific setup is the lack of an economic safety net. Historically, if the tech market crashed, the Federal Reserve would rapidly drop interest rates to soften the blow. However, because U.S. consumer inflation is stubbornly running at 3.7%—well above the Fed's 2% target—and global energy prices remain elevated, the central bank cannot cut rates without risking a devastating inflationary spiral.
The economy is effectively walking a tightrope: it is entirely dependent on speculative tech investments to stay afloat, while being continuously squeezed by the highest cost of capital seen in decades. If the AI capital loop snaps in late 2026, a hard landing by 2027 becomes the most probable outcome.
The IMF is providing the warning. The structural vulnerabilities are documented. The catalyst has a date on the calendar. All that remains is to see whether the market can pivot to profitability before the clock runs out—or whether the pieces fall exactly as the math suggests they will.
No Ads. By Us. For Us.
This article was made possible by readers like you. We hope it inspired you to support Emerald Book, so we can continue producing content like this.
We will never show you ads, sell your data, or require a subscription to consume our content. Your gift helps us keep the truth accessible.
Click the Support button to give a gift of any amount today.
Thank you for making this work possible.