
Emerald Pages
◆
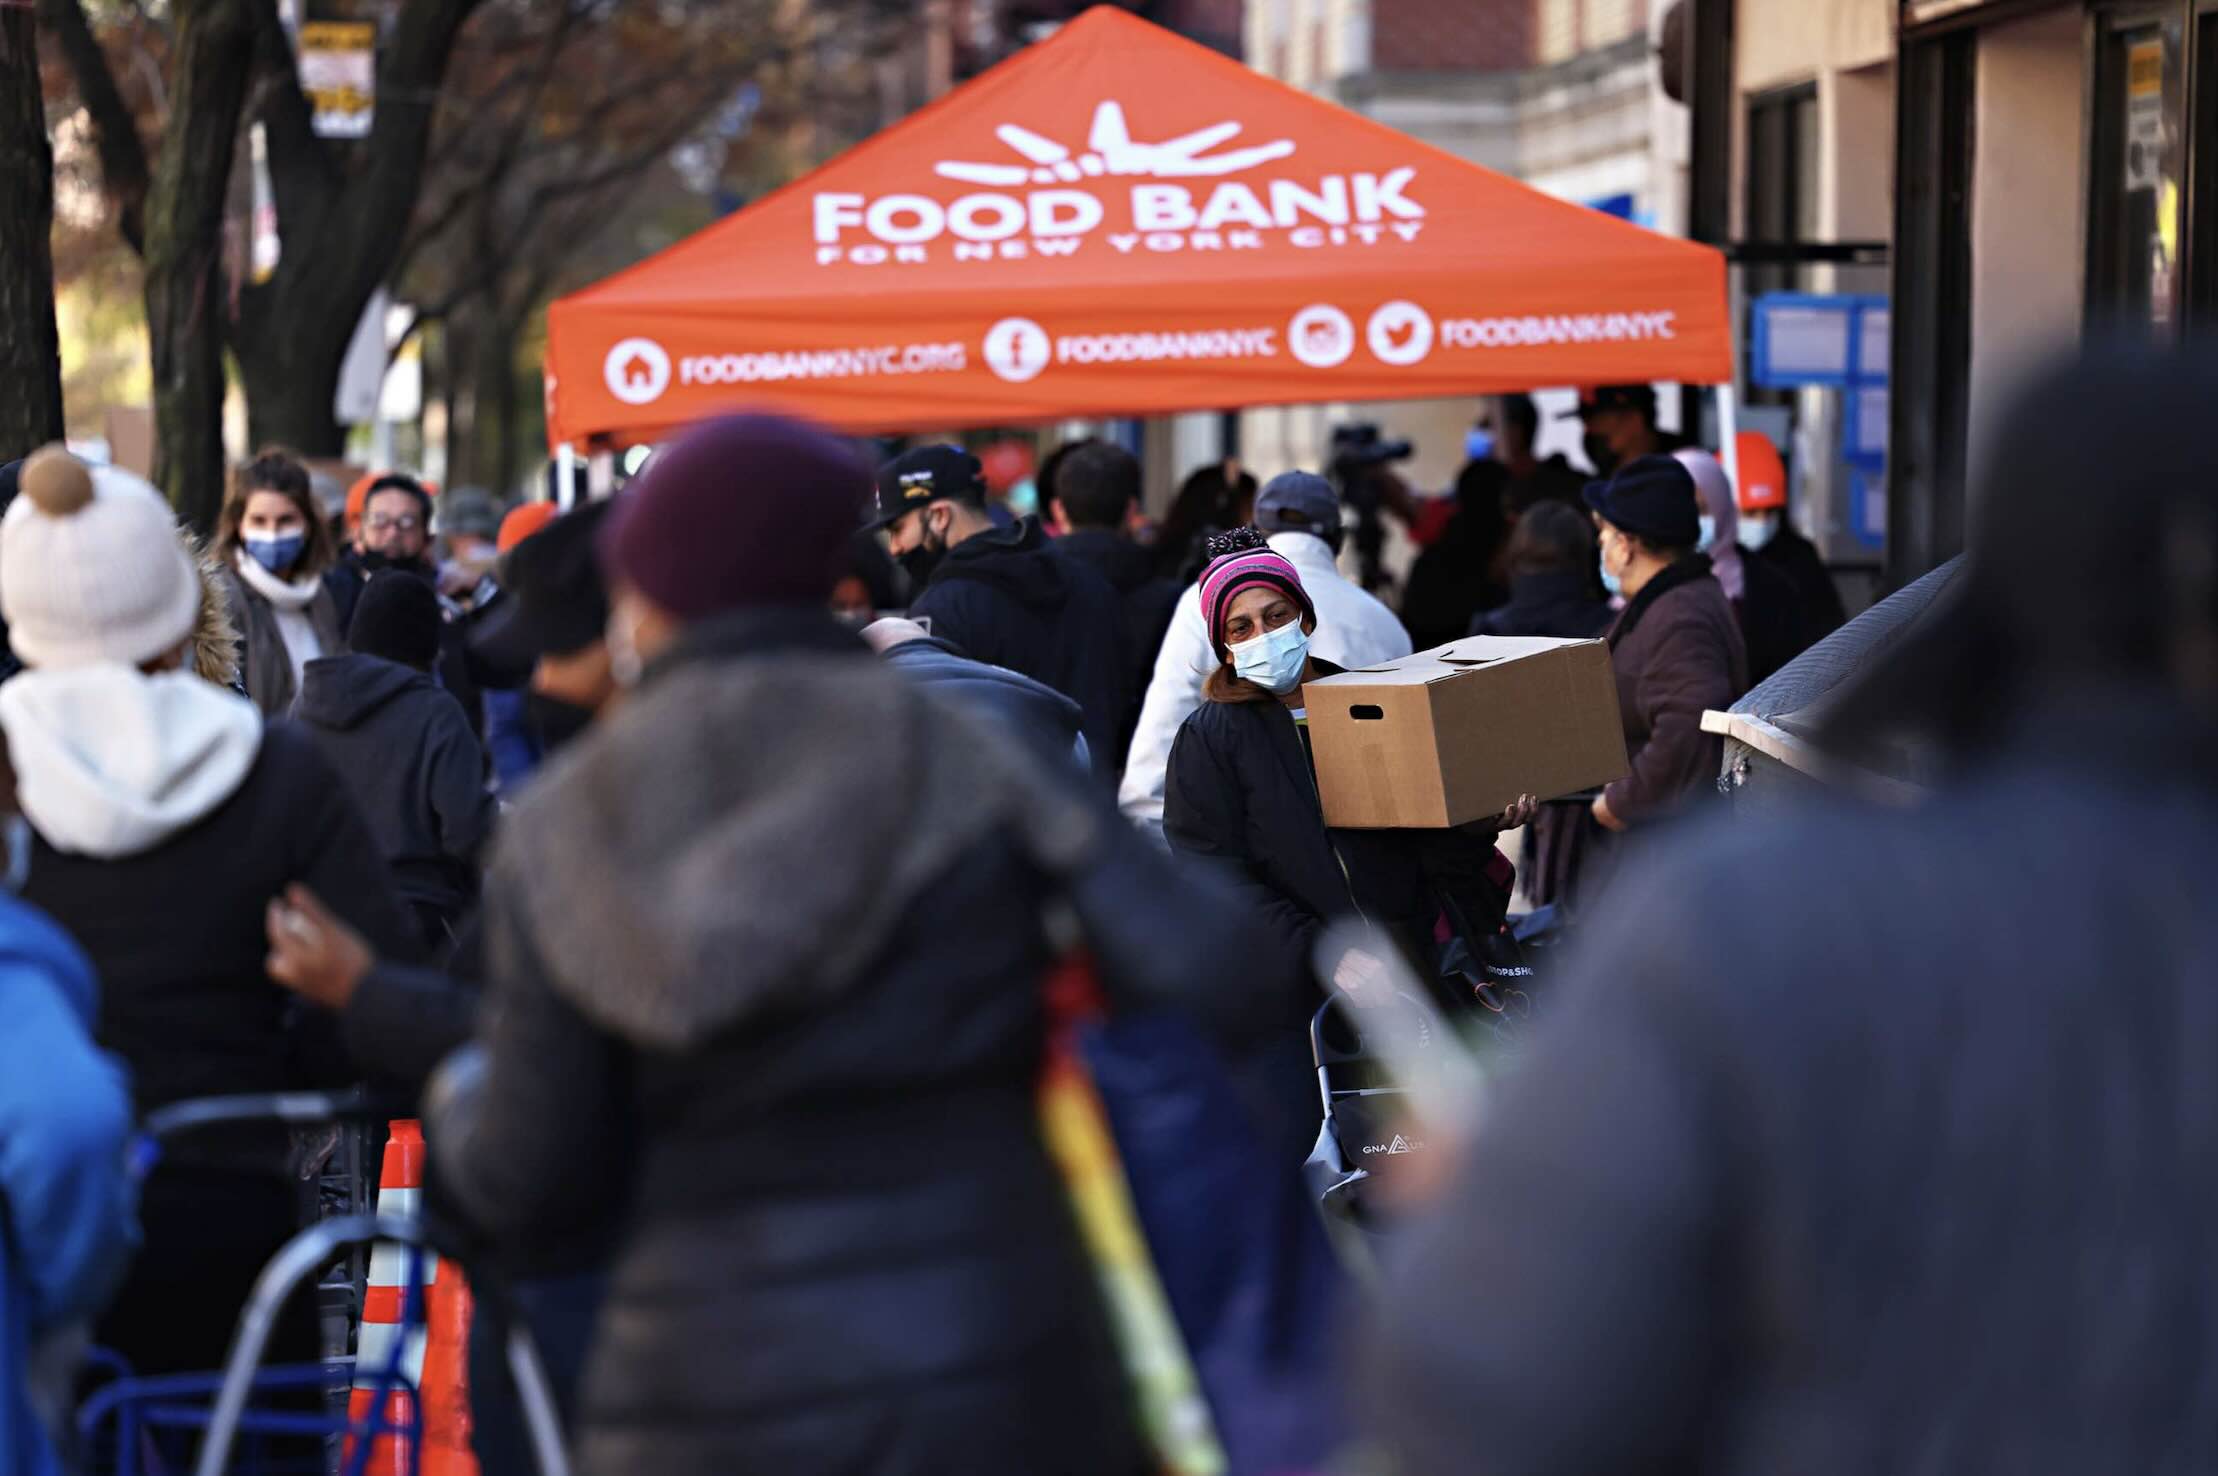
Photo: Getty Images
In the second quarter of 2026, U.S. household net worth hit an all-time high of $185.7 trillion. The Census Bureau reported that real median household income jumped 2.6% to a record $87,460. The poverty rate fell to a historic low. On paper, America has never been richer. Yet a staggering number of Americans say they feel financially worse off than they did five years ago.
They aren't imagining it. The gap between what the data celebrates and what households actually experience is the defining economic story of this decade — a disconnect built on a simple but devastating truth: wealth and income are not the same as cash flow, and averages hide more than they reveal.
To understand why record-breaking data can coexist with widespread financial anxiety, you have to look at how the money is actually divided. The average U.S. household net worth now floats above $1 million. But that number is heavily skewed upward by extreme concentration at the top. The top 10% of households own nearly 70% of all wealth. The richest 1% alone holds over 31%.
The Median Is Also a Mirage
The median household net worth — the true middle — sits closer to $192,900. That sounds like a decent cushion. But looking under the hood reveals why it's a mirage. For families in the median tier, the vast majority of that wealth is tied up in their primary home's equity and the family vehicle. You cannot go to the grocery store and spend $200 worth of your home's roof, nor can you pay for emergency dental care with your car's transmission.
Statistically, while the median net worth is close to $200,000, the median household has less than $10,000 in actual, liquid cash in checking and savings accounts. One major medical bill or a three-month job loss completely wipes them out. The national median income of $87,460 also ignores cost-of-living realities. In rural Mississippi (with an actual median income closer to $40,200), that income supports a comfortable middle-class life. In Seattle, Boston, or New York, that exact same income places a family under severe financial duress — functionally low-income, locked into permanent renting and paycheck-to-paycheck stress.
The Cash Flow Squeeze
The reason the higher cost of living feels so oppressive comes down to how wealth is built versus how it is spent. A massive portion of Americans' newfound wealth is locked up in home equity and retirement accounts. If your home value went up by $100,000, you are technically richer on paper. But that money is entirely inaccessible unless you sell your house or take on expensive debt. Meanwhile, the price spikes of the last few years have been concentrated heavily in things you cannot opt out of: housing, groceries, gas, utility bills, and insurance.
Since 2017, average American earnings grew by 43%. Over that exact same window, home prices surged 81% and rents climbed 54%. The average age of a first-time homebuyer has jumped from 29 years old in 1981 to 40 years old today. In 2019, the equivalent purchasing power of today's $87,460 income was roughly $66,700. That income gave a homebuyer a maximum affordable home price limit of $325,000, allowing them to comfortably shop roughly 55.7% of all active real estate listings. Today, despite the income number climbing, soaring interest rates and bloated valuations mean a median earner's maximum affordable home price has plummeted to $298,000. The share of affordable market listings has been cut in half to a mere 28%.
Living Off Debt
The dark secret of modern American prosperity is that much of it is built on a mountain of record-high consumer debt. When the media points to high consumer spending as proof that the economy is great, they are often tracking people using credit cards to buy basic necessities because their paychecks ran out. Total household debt sits at a jaw-dropping $17.94 trillion. Total auto loan debt has climbed to $1.64 trillion, with young and lower-income borrowers defaulting on car payments at rates not seen since the 2008 Great Recession.
When the Federal Reserve raised interest rates to fight inflation, it pushed the average credit card interest rate over 21% — the highest levels ever recorded. If a family carries a $6,000 balance just to cover the increased cost of rent and groceries, they are paying over $1,200 a year purely in interest without ever touching the actual principal. Next month's paycheck is already spent before it arrives, making it mathematically impossible to build the liquid savings buffer that would protect them from the next emergency.
The Savings Collapse
The U.S. Personal Saving Rate — the actual percentage of income people have left over after taxes and basic living costs — has cratered down to a mere 3.0%. For comparison, during the 1970s and 1980s, Americans routinely saved 10% to 12% of their income. This structural cash drought isn't happening because Americans suddenly forgot how to be disciplined with money. It is a direct math problem driven by a changing financial landscape.
When a sudden bill hits — like a $1,000 emergency room visit or a broken car transmission — only 30% of Americans can pay for it using cash savings. The rest are forced to put it on a credit card, take out a personal loan, or tap predatory lending networks. This converts an emergency into a high-interest monthly bill, destroying any future ability to save. Even the numbers celebrating retirement safety are out of context. A shocking 45.7% of working-age families do not own a retirement account at all. When you look at all working-age Americans and include the millions who have absolutely nothing saved, the overall median retirement account balance in the U.S. is just $955.
The Racial Wealth Gap: Hit Hardest, Least Protected
The median net worth for Black households is roughly $44,100, compared to $284,310 for White households. For every dollar of wealth a White family holds, a Black family has just 15 cents. Median Black household income sits near $56,020 — far below the national record of $87,460, which is driven primarily by higher earners. Experts estimate $190,000 is the baseline net worth for secure "middle class" status. The typical Black family operates far below it.
Three compounding forces widen the gap. First, the zero-savings squeeze: median liquid savings for Black households sit near $2,200 versus $10,000 for White households, so a 20% jump in rent or groceries cannot be absorbed — it becomes high-interest debt. Second, lockout from the asset shield: roughly 73% of White Americans own homes versus 43% of Black Americans, so most Black families face surging rents instead of benefiting from rising property values. Third, the intergenerational wealth drag: with less inherited wealth and family down-payment help, middle-income Black earners are more likely to send cash backward to support aging relatives.
The Only Metrics That Matter
Because macroeconomic numbers are built to evaluate a country's performance rather than human survival, the best approach is to discard them entirely when evaluating your own life. Instead, focus on your personal financial health architecture.
- Calculate Your "Months of Sovereignty": Divide your total liquid cash reserves by your absolute bare-minimum monthly survival costs. That number of months is your true wealth indicator — not a national median.
- Evaluate Your Fixed Cost Ratio: If your non-negotiable monthly commitments consume more than 50% of your take-home pay, you are in a cash-flow squeeze, regardless of what tier your income places you in.
- Track Your Debt-to-Income Direction: True economic freedom isn't matching a benchmark; it's watching your liabilities consistently trend downward while your liquid cash baseline trends upward.
- Build a Micro-Buffer First: Forget the daunting goal of a 6-month emergency fund. Focus strictly on reaching $1,000 in a separate, dedicated High-Yield Savings Account. This minor barrier stops 80% of common emergencies from turning into high-interest debt cycles.
The record-breaking economy is real — for those who own assets. For everyone else, it is a treadmill: running significantly faster just to stand in the exact same room they occupied seven years ago. The headline wealth is out of context. The cash flow squeeze is not. And until the metrics used to measure American prosperity reflect the lived reality of the median household, the gap between what the data says and what people feel will only continue to grow.
No Ads. By Us. For Us.
This article was made possible by readers like you. We hope it inspired you to support Emerald Book, so we can continue producing content like this.
We will never show you ads, sell your data, or require a subscription to consume our content. Your gift helps us keep the truth accessible.
Click the Support button to give a gift of any amount today.
Thank you for making this work possible.